Delta revenue jumps 18% as rising costs squeeze margins
Delta Corporation's revenue increased by 18.1 percent to US$607.5 million in the six months ended September 30, 2026, but rising operating costs weighed on margins, raising questions about how much further the country's largest beverages manufacturer can grow without improving cost efficiency.
The company's unaudited half-year results show that volumes increased by 6.7 percent, while earnings attributable to shareholders rose by nine percent to US$79.9 million.
Headline earnings per share (HEPS) increased by 14.6 percent to USc5.91, from USc5.15 recorded during the comparable period last year, while the interim dividend was raised by 20 percent to ZWG2.40 per share.
However, operating costs increased by 18.1 percent, matching revenue growth but significantly outpacing volume expansion, putting pressure on profitability.
The operating profit margin declined to 13.5 percent from 16 percent in the prior comparable period, while the EBITDA margin fell to 20.9 percent from 21.9 percent.
In its analysis of the results, Fincent Securities initiated coverage of Delta with a HOLD recommendation and a target price of USc123, arguing that the company's strong operating performance was increasingly reflected in its share price.
"The rating is about price, not the business," the brokerage said, noting that Delta's share price had gained 137 percent over 12 months, compared with a 119 percent increase in the Zimbabwe Stock Exchange All Share Index.
Fincent said much of the share price appreciation had resulted from a re-rating of the stock rather than earnings growth, with its valuation indicating limited upside at prevailing prices.
The brokerage identified the company's strong cash generation, high returns on invested capital and net cash position as positives but warned that declining operating margins and outstanding tax assessments posed risks.
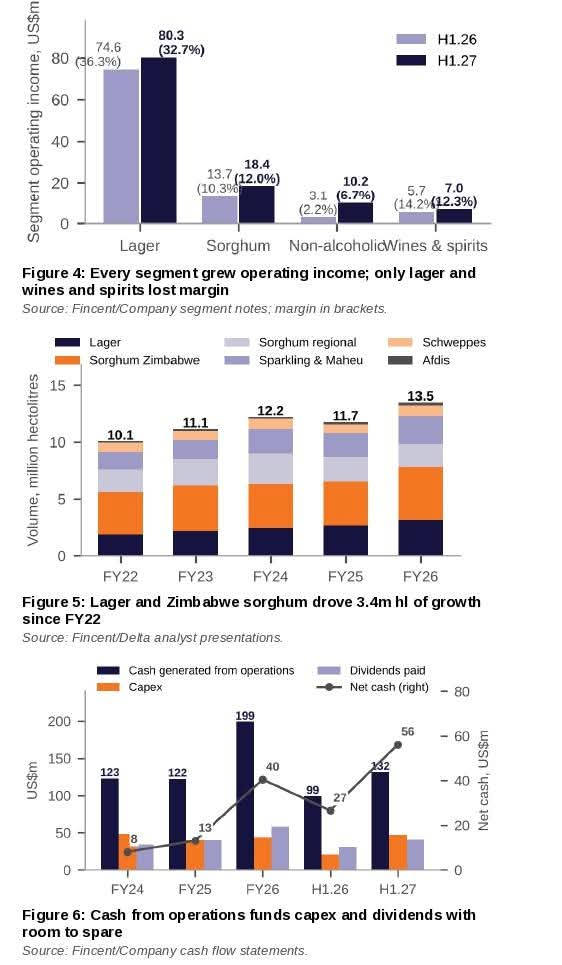
Delta closed the half-year with US$56.2 million in net cash after spending US$47.2 million on capital expenditure, more than double the US$20.5 million invested during the corresponding period last year.
Cash generated from operations stood at US$131.2 million, equivalent to approximately 104 percent of EBITDA, although this represented a 31.4 percent decline from the prior comparable period.
The lager segment remained the largest contributor to group profitability, accounting for 40 percent of revenue and 69 percent of segment operating income.
Lager revenue increased by 19.5 percent to US$245.3 million, supported by volume growth of 13.1 percent.
However, lager operating income declined by 1.7 percent to US$80.3 million, with the segment's operating margin falling from 38.3 percent to 32.7 percent.
Fincent attributed the pressure partly to supply constraints and the need to import AB InBev brands from sister breweries to meet demand, with the imported products carrying lower margins.
The brokerage expects investments in the Southern region and the planned expansion of the Belmont brewery to improve supply capacity and support margins.
Other segments delivered mixed performances, with sorghum beer revenue increasing by 15.1 percent to US$153 million, while operating income rose by 34.1 percent to US$18.4 million.
Non-alcoholic beverages recorded a 20.1 percent increase in revenue to US$99.2 million, while operating income more than tripled to US$10 million as operating margins improved from 2.4 percent to 10.1 percent.
Wines and spirits revenue grew by 44.9 percent to US$58.5 million, although volumes declined by 15 percent, while Schweppes revenue increased by 58.9 percent to US$55.9 million.
Despite revenue growth across all segments, Fincent warned that high operating costs, taxation and currency-related risks could constrain future profitability.
The brokerage also highlighted US$74.2 million in outstanding Zimbabwe Revenue Authority (ZIMRA) tax assessments as a potential risk, alongside the impact of the sugar tax, imported inputs and foreign currency pressures.
For the full financial year, Fincent forecasts revenue of US$1.26 billion and HEPS of USc12.70, with earnings expected to improve further in FY28 as additional brewing capacity comes on stream.
It said investors should monitor operating margin performance, the commissioning of the Belmont brewery and the outcome of the outstanding tax dispute.
Fincent maintained that Delta remained a cash-generative business with strong market positions but argued that its current valuation left limited room for further share price appreciation without a stronger recovery in margins.

About Oscar Jeke - Reporter
Staff Writer