


About 70 percent of Zimbabweans have no insurance, while roughly nine in 10 are not actively contributing to a pension, leaving millions exposed to financial shocks and uncertain retirement prospects.
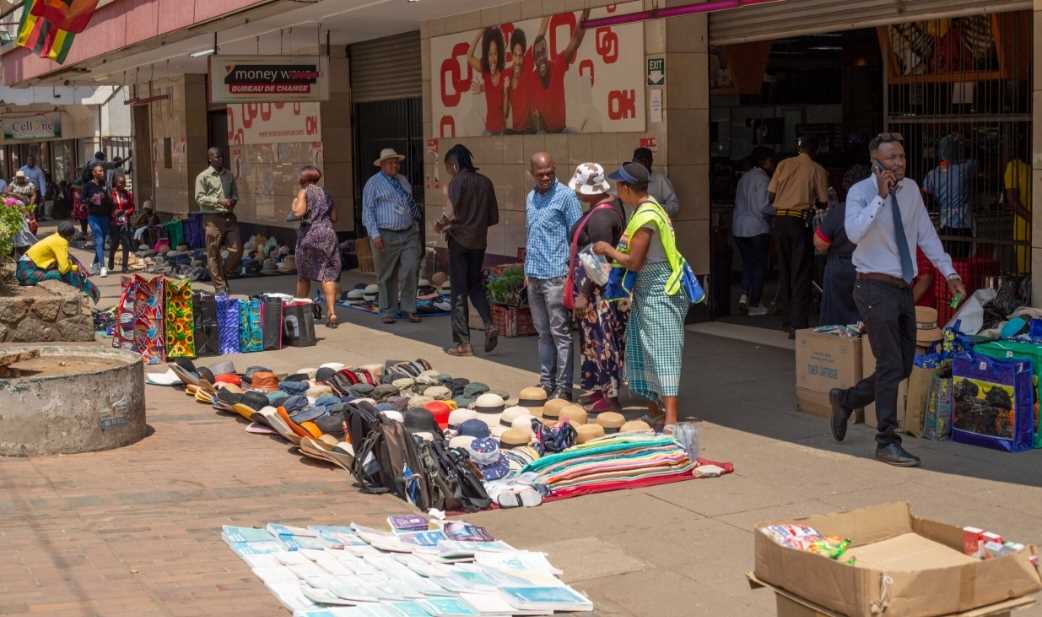
The gap is being driven in part by the country’s large informal economy, with 76 percent of businesses operating outside the formal sector.
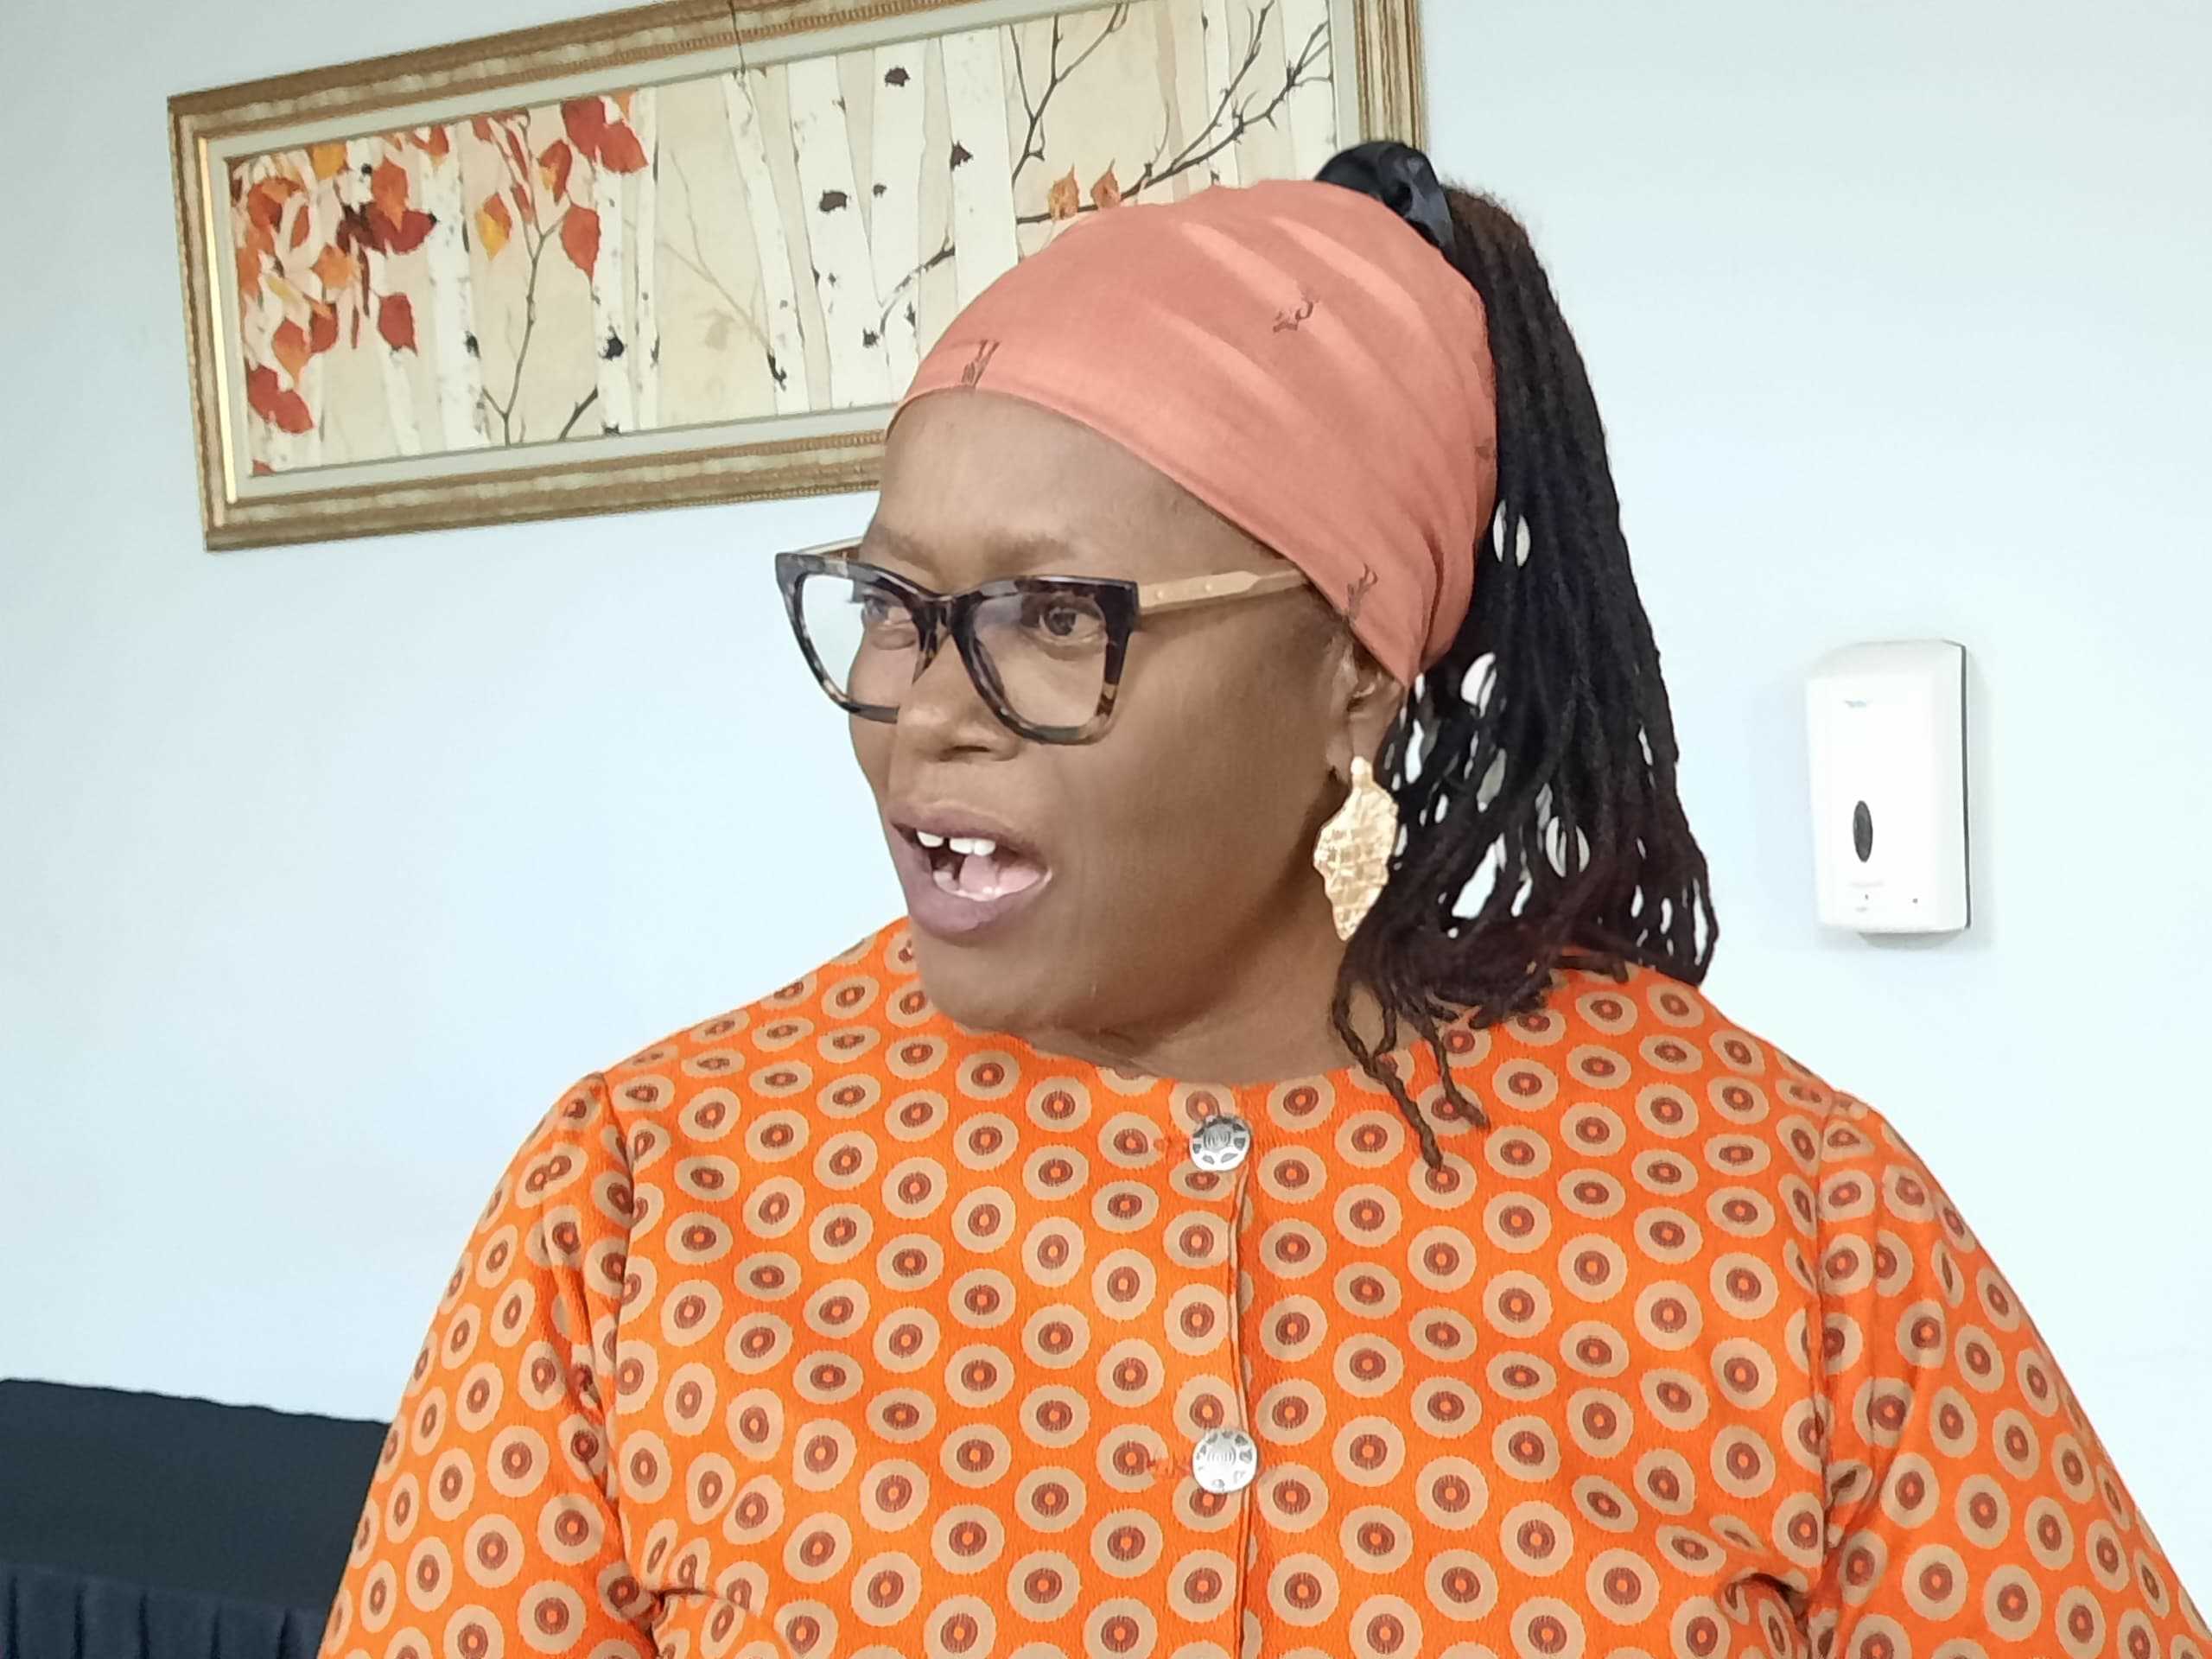
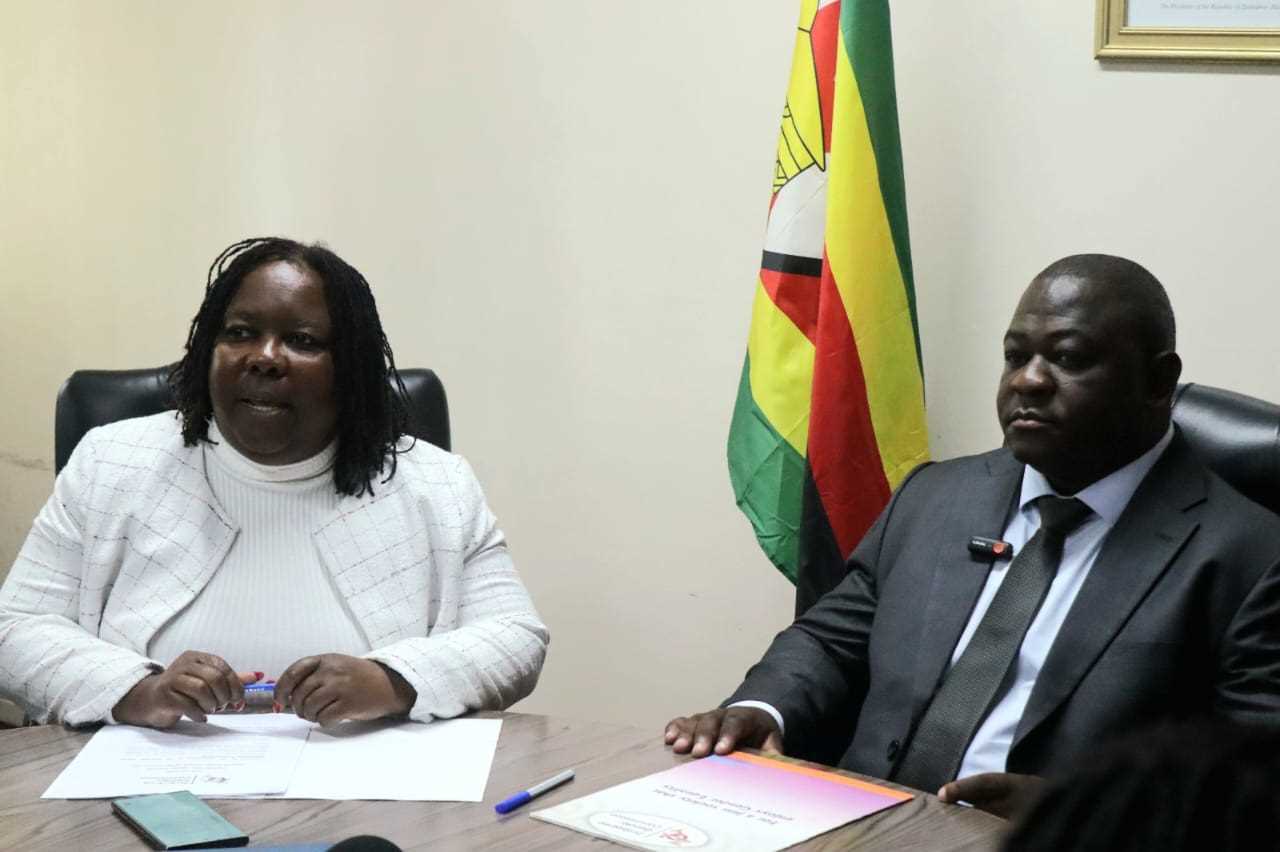
Insurance and Pensions Commission Commissioner Grace Muradzikwa said the regulator was pushing for simpler and more affordable products that can accommodate people with irregular incomes.
“In an economy where 76% of businesses are informal,” Muradzikwa said, IPEC is “pushing for simpler insurance products to broaden cover.”
The figures highlight a challenge for an industry traditionally built around formal employment, regular salaries and predictable monthly contributions.
Informal workers and businesses often have fluctuating incomes, limited documentation and little access to employer-sponsored insurance or retirement schemes.
As a result, households facing illness, death, accidents, business losses or other emergencies may have to rely on savings, borrowing, selling assets or financial support from relatives.
Related Stories
The same challenge extends into retirement.
Workers outside formal employment are less likely to have employer-linked pension schemes, while irregular earnings can make fixed monthly contributions difficult to maintain.
Many could therefore face retirement with limited savings and may have to rely on family support, personal savings or continue working for longer.
For IPEC, expanding coverage means designing financial products around how people actually earn and spend money rather than expecting informal workers to fit into a formal-employment model.
Microinsurance is one way of extending basic protection through lower premiums and smaller contributions. However, affordability alone may not solve the problem if products remain difficult to access, poorly understood or structured around regular incomes that informal workers do not have.
Low participation in insurance and pensions also affects the wider economy.
Insurance can provide households and businesses with a financial cushion when unexpected losses occur, while pension contributions create pools of long-term savings that can be invested in the economy.
Increasing participation could therefore help households withstand financial shocks while also expanding Zimbabwe’s pool of domestic savings.


Leave Comments